Should You Buy a House at 7% Interest Rates? An Omaha Realtor's Honest Take

David Matney • September 8, 2026

The question I hear most right now isn't about neighborhoods or square footage. It's this: *Should I buy a house when rates are at 7%?* I get it. That number feels heavy compared to the sub-3% days we saw a few years ago. Your monthly payment is higher. The math doesn't feel as friendly. And every headline seems to whisper that maybe, just maybe, you should wait for rates to drop.

But here's the thing: the rate is only one piece of the puzzle. I've watched buyers sit on the sidelines for months, convinced that 5% rates are around the corner, only to see home prices climb and competition heat back up. I've also seen people jump in without thinking through their job stability or how long they plan to stay, and that rarely ends well. The truth is, whether 7% makes sense for you depends on factors that have nothing to do with what the Fed might do next quarter.

In this article, I'm going to walk through the real considerations that should drive your decision: monthly payment affordability, how long you plan to own the home, your job and income stability, your down payment, what seller concessions and rate buydowns can do for you right now, and the risks of banking on a future refinance. We'll also talk about why waiting for lower rates could help you, or completely backfire if prices and competition surge before rates ever drop. This isn't about timing the market perfectly. It's about making a decision that works for your life, your budget, and your timeline.

Table of Contents

Monthly Payment Affordability: The Real Bottom Line

Let's start with the most important number: your monthly payment. Not the rate. Not the purchase price. The payment. Because that's what you'll live with every month, and if it doesn't fit your budget comfortably, nothing else matters.

At 7%, your payment is higher than it would have been at 3% or even 5%. That's just math. But the question isn't whether the payment is higher than it used to be. The question is whether you can afford it without stretching so thin that one surprise expense, a car repair, a medical bill, a furnace replacement, puts you in a bind. I tell buyers to look at their take-home pay and ask: can I cover this payment, plus property taxes, plus insurance, plus maintenance, and still have room to save and live? If the answer is yes, the rate becomes less important. If the answer is no, it doesn't matter if rates are 7% or 4%, you're not ready.

One thing I see right now is buyers who qualify for a certain payment but don't feel comfortable with it. That gut check matters. Lenders will approve you for more than you might want to spend. They're looking at ratios. You're looking at your life. If the payment feels tight, it probably is. On the other hand, if you've run the numbers and the payment fits, don't let the rate itself scare you off. A 7% rate on a home you can afford is better than a 5% rate on a home that stretches you too far.

How Long You Plan to Own the Home

The second factor is your timeline. How long do you plan to stay in this house? If you're buying a starter home and you know you'll move in three years, a 7% rate is going to sting. You'll pay a lot of interest up front, build very little equity, and then face transaction costs when you sell. That's a tough equation.

But if you're buying a home you plan to live in for seven, ten, or fifteen years, the rate matters less. Over time, you'll build equity through appreciation and principal paydown. You'll spread your closing costs over more years of use. And if rates do drop, you'll have the option to refinance, but you won't be dependent on it. The longer your timeline, the more the purchase price and the home itself matter, and the less the rate does.

I've had buyers tell me they're planning to stay five to seven years, and they're on the fence about whether that's long enough. Honestly, five years is usually the break-even point where buying starts to make more sense than renting, assuming normal appreciation. Seven years or more, and you're in good shape. Less than that, and you need to be really confident in your local market and your ability to sell without losing money.

Job Stability and Income: The Foundation of Any Purchase

This one doesn't get talked about enough. Your interest rate doesn't matter if you lose your job six months after closing. I know that sounds harsh, but it's the reality. Before you buy, you need to have a clear picture of your income stability. Are you in a secure position? Is your industry stable? Do you have an emergency fund that could cover your mortgage for three to six months if something goes wrong?

If you're in a job transition, or you're self-employed with variable income, or you're in an industry that's facing layoffs, buying right now, at any rate, might not be the right move. On the other hand, if you have a stable job, a solid emergency fund, and confidence in your income, a 7% rate is just a number you can plan around. The foundation of any home purchase is your ability to make the payment, month after month, no matter what the market does.

I also tell buyers to think about dual incomes. If you're relying on two incomes to make the payment, what happens if one of you loses a job or decides to stay home with kids? Can you still cover it? These aren't fun questions, but they're the ones that keep you from becoming a distressed seller two years down the road.

Down Payment: How Much You Bring Changes Everything

Your down payment has a huge impact on how a 7% rate feels. If you're putting down 3% or 5%, your loan amount is higher, your monthly payment is higher, and you're paying PMI on top of everything else. That can make a 7% rate feel really expensive. If you're putting down 20%, your payment is lower, you avoid PMI, and the rate doesn't sting as much.

I'm not saying you need 20% to buy. Plenty of buyers use low-down-payment programs and do just fine. But you need to understand how your down payment affects your monthly budget. A bigger down payment also gives you more equity from day one, which matters if you need to sell sooner than planned or if the market softens.

Right now, I'm seeing buyers who saved up a solid down payment and are using it to buy down their rate or negotiate better terms. That's a smart play. I'm also seeing buyers who are stretching to buy with very little down, and they're the ones who feel the 7% rate most acutely. If you don't have much saved, it might make sense to wait, not for rates to drop, but to build up your down payment so the payment is more manageable.

Seller Concessions and Rate Buydowns: Tools You Can Use Right Now

Here's where the current market gives you some leverage. Sellers are more willing to offer concessions than they were a year ago. That might mean they'll cover some of your closing costs, or they'll agree to a rate buydown that drops your interest rate for the first few years. A 2-1 buydown, for example, can give you a 5% rate in year one, 6% in year two, and then 7% after that. That can make a big difference in your early payments and give you time to adjust or refinance.

I've had buyers negotiate $10,000 or $15,000 in seller concessions that they used to buy down their rate. That's money you wouldn't have gotten in a hot market. Right now, with more inventory and less competition, you have room to ask. Don't assume the list price and the rate you're quoted are set in stone. Work with your lender and your agent to see what's possible.

Rate buydowns aren't free, the seller is essentially prepaying some of your interest, but if they're willing to do it, it can make a 7% rate feel a lot more like a 5% rate, at least for a while. And if you're planning to refinance in a couple of years anyway, a buydown can be a great bridge.

The Refinance Gamble: Why Counting on Lower Rates Is Risky

A lot of buyers are telling me they'll just refinance when rates drop. And look, that's possible. Rates could come down. But it's not guaranteed, and it's not a strategy you should rely on. Here's why: refinancing costs money. You'll pay closing costs again, usually 2% to 3% of your loan amount. If rates drop to 5.5% instead of 5%, is it worth it? Maybe not. If rates drop but your home value hasn't increased, you might not have enough equity to refinance without PMI. If your income or credit changes, you might not qualify.

I've seen buyers get stuck in loans they thought were temporary. They bought assuming they'd refinance in two years, and then rates stayed flat, or they lost their job, or their credit took a hit, and suddenly they're locked in. If you buy at 7%, you need to be okay with 7%. Treat a future refinance as a bonus, not a plan.

That said, if rates do drop significantly, refinancing is absolutely an option. Just don't let it be the reason you buy a home you can't afford right now.

Waiting for 5% Rates: What Could Go Right (and Wrong)

So what if you wait? What if you sit tight and hope for 5% rates? It could work. If rates drop and prices stay flat, you'll get a better deal. Your payment will be lower, and you'll have more buying power. That's the best-case scenario.

But here's the risk: if rates drop, everyone else is waiting too. The moment rates hit 5.5% or 6%, buyers flood back into the market. Demand spikes. Prices go up. Competition heats up. You might end up paying $20,000 or $30,000 more for the same house, which wipes out any savings from the lower rate. I've seen this happen. Buyers wait for the perfect moment, and by the time it arrives, the market has moved past them.

There's also the risk that rates don't drop as much as you hope, or they drop and then climb again. The Fed doesn't control mortgage rates directly, and the bond market is unpredictable. If you wait a year and rates are still at 6.5%, you've spent a year paying rent instead of building equity. That's not nothing.

Waiting makes sense if you're not ready to buy, if your finances aren't stable, if you don't have a down payment, if you're not sure where you want to live. But if you're ready and you're just waiting for a better rate, you're gambling. Sometimes the gamble pays off. Sometimes it doesn't.

Which Strategy Is Right for You?

So how do you decide? Here's how I think about it:

Buy now if:

  • Your monthly payment is comfortable and fits your budget with room to spare.
  • You plan to stay in the home for at least five to seven years.
  • Your job and income are stable, and you have an emergency fund.
  • You have a solid down payment, or you're using a low-down-payment program you understand.
  • You can negotiate seller concessions or a rate buydown to ease the payment.
  • You're okay with the rate you're getting and not counting on a refinance.

Wait if:

  • The payment stretches your budget too thin, even with concessions.
  • You're not sure where you want to live or how long you'll stay.
  • Your job or income is uncertain, or you don't have an emergency fund.
  • You need more time to save for a down payment.
  • You're only buying because you think you have to, not because you're ready.

The right answer depends on your situation, not the market's. I can't tell you whether rates will be 5% next year or 8%. Nobody can. What I can tell you is that if you wait for perfect conditions, you'll be waiting forever.

Final Thoughts: Buy When It Makes Sense for You

A 7% interest rate isn't ideal. I'm not going to pretend it is. But it's also not a reason to put your life on hold if you're ready to buy. I've worked with buyers who got 7% rates, negotiated smart concessions, and bought homes they love. They're building equity. They're not paying rent. And if rates drop, they'll refinance. If rates don't drop, they're still in a home that works for them.

The worst thing you can do is make a decision based on fear or FOMO. Don't buy because you're afraid of missing out. Don't wait because you're afraid of overpaying. Look at your budget, your timeline, your stability, and your goals. If buying makes sense for you right now, the rate is just a number you'll work around. If it doesn't make sense, no rate will fix that.

If you're trying to figure out whether now is the right time for you, let's talk. I can walk you through the numbers, show you what's available, and help you think through the trade-offs. No pressure, no sales pitch, just a conversation about what makes sense for your situation. Reach out, and let's figure it out together.

FAQ: Buying a Home at 7% Interest Rates

Is 7% a bad interest rate for a mortgage?

It's higher than the historic lows we saw a few years ago, but it's not unusually high by long-term standards. Whether it's bad for you depends on your budget and timeline. If the payment works and you're planning to stay in the home for several years, the rate is less important than the overall affordability and fit of the home.

Should I wait for interest rates to drop before buying?

Waiting could save you money if rates drop and prices stay flat, but it's a gamble. If rates drop, buyer competition usually increases, which can drive prices up and wipe out your savings. If you're ready to buy and the payment works, waiting might cost you more in the long run.

Can I refinance later if rates go down?

Yes, refinancing is an option if rates drop significantly. But it's not free, you'll pay closing costs again, usually 2% to 3% of your loan amount. Don't buy a home assuming you'll refinance. Buy a home you can afford at the rate you're getting, and treat a future refinance as a bonus.

What is a rate buydown, and should I use one?

A rate buydown is when the seller or you pay upfront to lower your interest rate for the first few years. A 2-1 buydown, for example, might give you a 5% rate in year one and 6% in year two before jumping to 7%. If the seller is willing to cover the cost, it can make your early payments much more manageable and give you time to adjust or refinance.

How much should I put down when rates are high?

A larger down payment lowers your loan amount and your monthly payment, which helps offset a higher rate. If you can put down 20%, you'll also avoid PMI. But don't drain your savings to hit 20% if it leaves you without an emergency fund. Find a balance that keeps your payment affordable and your finances stable.

What if I can't afford the payment at 7%?

If the payment doesn't fit your budget comfortably, don't buy. It's better to wait, save more for a down payment, or look at less expensive homes than to stretch yourself too thin. A lower rate won't help if you can't make the payment in the first place.

DAVID MATNEY

David Matney is a trusted Realtor® and local expert with over 20 years of experience in Omaha’s real estate market. 

OMAHA RELOCATION GUIDE

img

WATCH OMAHA VIDEOS

A man with glasses looks concerned, with a map of Nebraska and the text 'NEBRASKA COLLAPSE' in bold letters.
By David Matney • October 30, 2026
Home prices haven't crashed, but affordability is eroding. Learn how we got here, why rates haven't brought prices down, and what needs to happen next in Omaha.
A man with glasses looks shocked in front of a colorful graphic of Omaha's skyline and housing market trends.
By David Matney • October 22, 2026
Omaha housing market October 2026: inventory down 6.3%, sales down 11.7%, prices up 3.1%. What buyers and sellers need to know about Douglas and Sarpy County.
A frustrated woman points at an HOA violation sign in front of a house while a concerned man looks on.
By David Matney • October 21, 2026
Can an HOA foreclose on your home? Let's break down special assessments, rising fees, and the critical questions to ask before buying.
Aerial view comparing a barren landscape to a developed area with water features and buildings.
By David Matney • October 15, 2026
From Avenue One's 200-acre Main Street to Sarpy County's $110M expressway, explore 11 major Omaha developments reshaping West Omaha, Downtown, and beyond.
The Advantages of Buying in 2026: Less Competition, More Negotiating Room — Okay, I'm, Would
By David Matney • October 14, 2026
Mortgage rates above 7%, rising prices, and higher costs make 2026 tough for Omaha buyers. But there's a room to negotiate. Here's what you need to know.
Omaha Housing Market: Is a Crash Coming or Is Everything Changing?
By David Matney • October 8, 2026
Omaha's housing ladder has stalled. First-time buyers now enter in their 30s and 40s, equity-rich sellers won't move, and multi-generational living is reshaping demand.
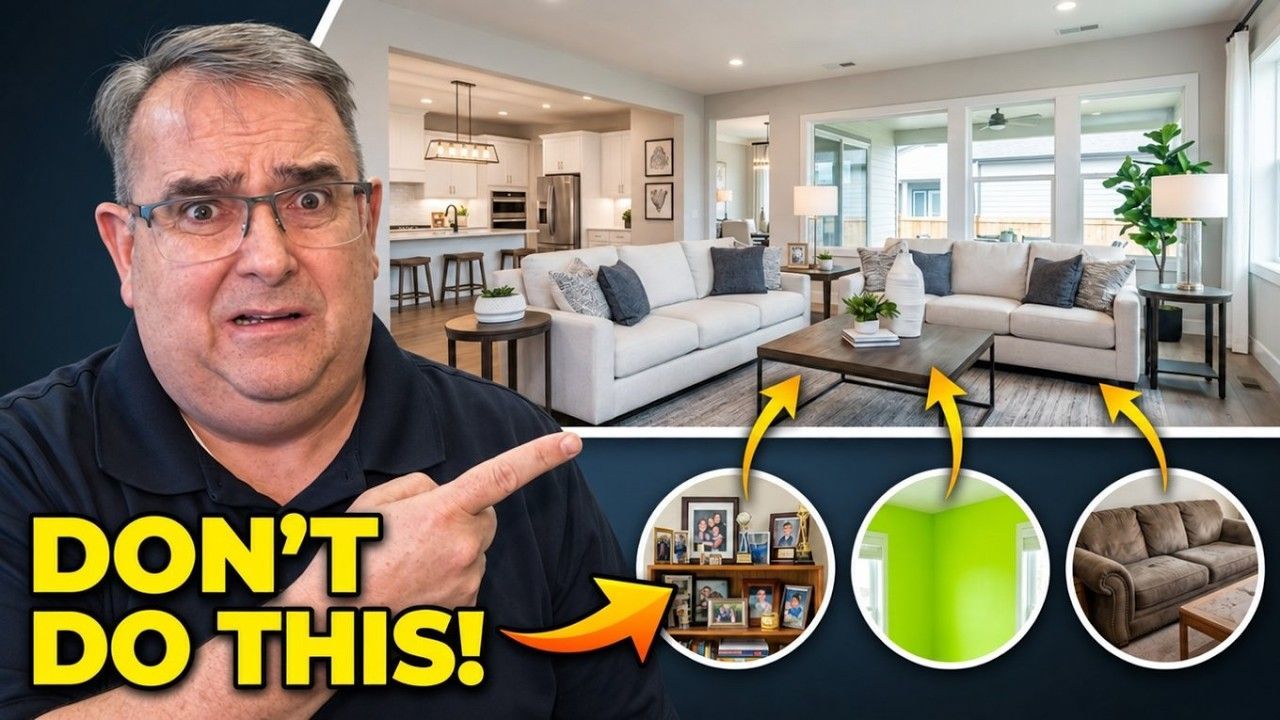
Three Things Every Seller Should Do Before Listing — That's, Wow, Yeah
By David Matney • October 7, 2026
Omaha agent David Matney and professional stager Susan Evans reveal the biggest staging mistakes sellers make and how to present your home to sell faster.
This allows hyperscale data center developers to build co-located power plants to help meet their massive energy needs
By David Matney • October 1, 2026
Data centers are reshaping Douglas and Sarpy Counties. Learn how proximity to these facilities affects home values and what you need to know before relocating.
known as Field Club.
By David Matney • September 24, 2026
From Field Club to Old Loveland, discover where Omaha's wealthiest families lived as the city grew west. Historic mansions, architectural character, and what these neighborhoods are like today.
that backdrop looking over that river, which was a— which is the Eagle Creek is what they call
By David Matney • September 23, 2026
Thinking about buying hunting land or a weekend getaway in Nebraska? Learn what to ask about access, utilities, financing, and hidden costs before you buy.
Show More